
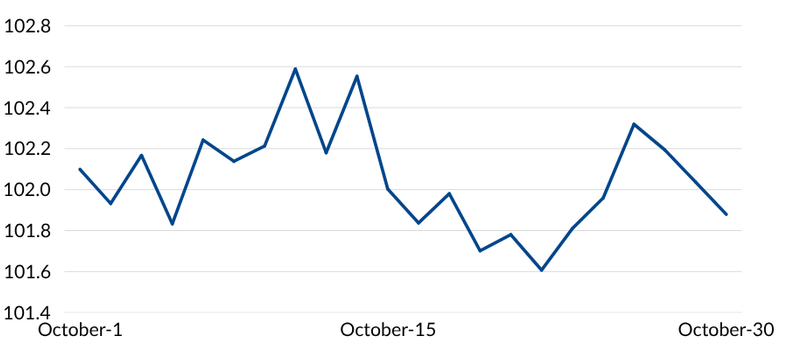
US dollar was mixed in October, as hawkish Fed signals failed to translate into broad-based gains. Softer-than-expected unemployment data remained a concern with non-farm payrolls increasing by 29K vs. 90K expected, while unemployment rose to 4.2% vs. 4.1% expected. Hawkish Fed minutes and stronger-than-expected inflation at 3.7% YoY vs. 3.6% expected, supported expectations that monetary policy would remain restrictive. However, renewed concerns around the AI theme weighed on perceptions of US exceptionalism. The Fed’s left rates unchanged as widely expected, with two dissentions in favor of a hike. While Chair Warsh sought to characterize the decision as a “hawkish hold,” the lack of forward guidance left markets focused on the possibility of a less hawkish policy path going forward.
EUR | Euro was the worst performing currency in the G10 in October, pressured from French political uncertainty and elevated energy costs. 10Y OAT-Bund yield spreads reached the highest level since 2012 on instability in France. Although inflation printed higher than expected at 3.8% YoY vs. 3.7% consensus, the ECB kept rates unchanged. While balancing downside growth risks against upside inflation risks, the central bank indicated a likely further hike should data remain in line with ECB expectations.
GBP | Sterling was a middling performer within the G10 in October, balancing global risk sentiment and UK budget uncertainty. The global bond sell-off and elevated energy prices weighed on Sterling, although better-than-expected GDP of 0.1% MoM vs. -0.1% consensus helped temper the pressure. Inflation printed higher than anticipated at 3.5% YoY vs. 3.4% expected, although core was in-line at 2.8%. While the October Autumn budget provided some stability, the growth outlook remained concerning.
JPY | Yen underperformed the G10 save a weaker Euro in October. While the possibility of GPIF shifting assets back domestically was supportive, the BoJ indicated that underlying inflation had reached target levels. Rates were left unchanged at its meeting, with Governor Ueda saying that the bank would continue to assess the need for a rate increase at each policy meeting. In addition, the BoJ announced that it would nearly triple the pace of sales of its ETF holdings from January.
CHF | Swiss franc landed in the top half of the G10 in October. Inflation printed in line with expectations at 1.0% YoY from 0.8% previously, as the SNB showed no signs of action within domestic sight deposits. Unemployment remained steady at 3% as retail sales jumped to 3.2% from a revised 2.8% a month earlier.
CAD | Canadian dollar was a strong performer within the G10 in October. With concerns surrounding AI increasing, elevated oil prices were supportive to Canadian dollar rather than primarily reinforcing US dollar’s safe-haven appeal. The BoC raised interest rates by 25bps to 2.50% as expected, the first increase in three years. The central bank maintained a cautious stance, increasing its inflation projections while noting a potential need to raise the policy rate further. Employment data was weaker than expected, losing -68.3K instead of the expected gain of 10.0K.
AUD | Australian dollar landed in the top half of the G10 in October as relative carry continued to provide support. Hawkish commentary from the RBA and stronger than expected inflation at 4.3% YoY vs. 4.2% consensus helped Australian dollar offset weaker employment, which fell -39.3K instead of the expected gain of 20.0K.
| Change 1M % | FX Rate | |||
|---|---|---|---|---|
 | EUR |  | -1.72% | 1.1163 |
 | GBP |  | 0.84% | 1.33965 |
 | JPY | | -0.22% | 157.485 |
 | AUD | | 1.12% | 0.7035 |
 | CAD | | 1.71% | 1.39585 |
 | CHF | | 1.45% | 0.82305 |
| Source: WM/Reuters | ||||
Mesirow Currency’s Extended Markets Currency Alpha, Asian Markets Currency Alpha, Emerging Markets Currency Alpha and Systematic Macro strategies all ended up with positive returns in October. Our Fundamental Strategy performed positively across all strategies. The non-correlated, mean reverting, and machine learning models in our Technical strategy all contributed to gains this month while the trend following models detracted.
Connect with us to learn more about Mesirow Currency solutions

Customized solutions to manage unrewarded currency risk in international portfolios.

Strategies that aim to profit from short and medium-term moves in the currency market.

Trading solution for asset managers and owners with focus on reducing transaction costs, improving transparency and enhancing efficiency.
The information contained herein should not be construed as a recommendation to purchase or sell any particular security or investment vehicle offered by Mesirow . The information included has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. Any opinions expressed are subject to change without notice. Mesirow Financial Investment Management, Inc. and its affiliated companies and/or individuals may, from time to time, own, have long or short positions in, or options on, or act as a market maker in, any securities discussed herein and may also perform financial advisory or investment banking services for those companies. It should not be assumed that any recommendations incorporated herein will be profitable or will equal past performance. Any stated performance results include the reinvestment of dividends and other earnings. Investment management services offered by Mesirow Financial Investment Management, Inc., an SEC-registered investment advisor.